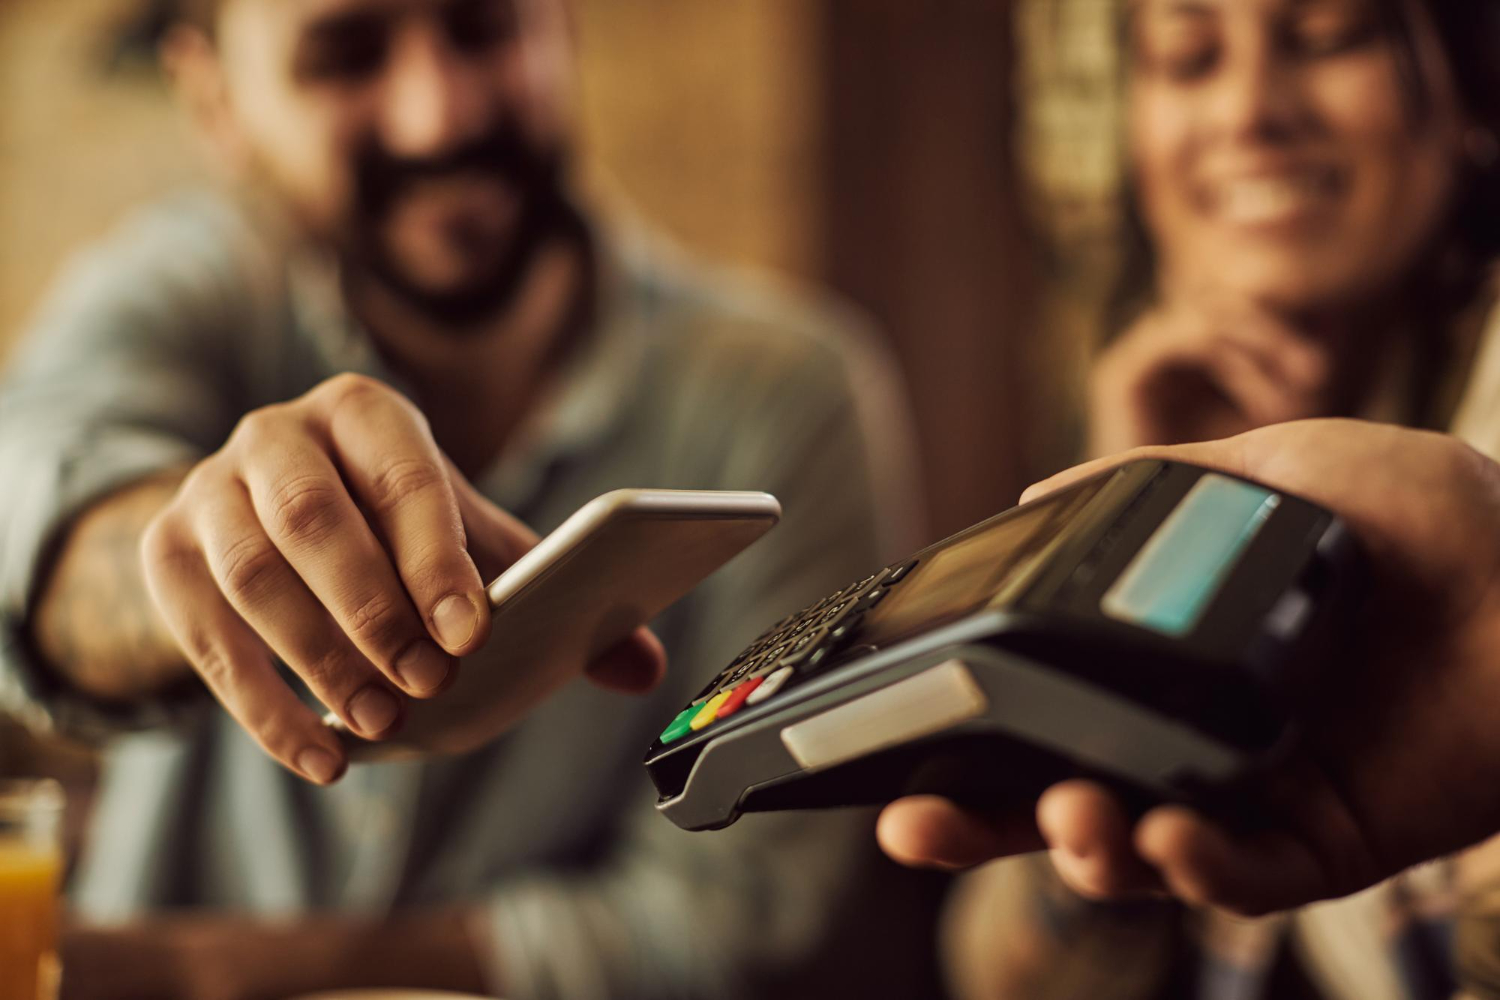
Payment infrastructure used to be built around large, infrequent transactions. A mortgage, a car purchase, a business invoice- these were the use cases that shaped how money moved. The internet changed the transaction profile entirely. People now make dozens of small payments daily: a subscription renewal, a digital download, a quick top-up. The systems handling these payments have had to change just as fast.
What is happening underneath the surface of modern payments is more significant than most users realize, and it is reshaping how money moves across every online sector.
Why Transaction Volume Has Outpaced Legacy Systems
Traditional payment rails were engineered for batch processing. Banks would settle transactions in overnight cycles, which worked fine when volume was low and amounts were high. That model breaks under the pressure of real-time digital commerce. A single platform today might process thousands of micro-transactions per hour, each one needing near-instant confirmation to keep the user experience from stalling.
Legacy card networks were retrofitted to handle this load, but retrofitting has limits. The infrastructure now sitting beneath platforms like Apple Pay, Google Pay, and open banking APIs is fundamentally different. It is designed for speed, parallelism, and low overhead per transaction. The old architecture was built like a highway with toll booths at every exit. The new one removes most of those stops entirely.
The shift also changed what counts as a payment. Splitting a restaurant bill, paying for in-app content, topping up a prepaid account- these are all transactions now. Infrastructure providers had to expand their definition of what a payment is before they could build something capable of handling all of them at scale.
Zero-Friction Checkout and How It Changed User Behavior
Checkout friction is one of the biggest reasons online payments fail. Asking a user to enter a 16-digit card number, an expiration date, and a CVV introduces multiple points where they can drop off entirely. Research across e-commerce consistently shows that the longer a checkout form, the lower the conversion rate. Reducing that form, or eliminating it, directly increases completed payments.
One of the clearest examples of zero-friction payment in practice is the phone billing model, where a user authorizes a charge that goes straight to their mobile phone bill or prepaid balance. No card details, no form fields, no waiting for an OTP from a bank. The charge is confirmed in seconds using the mobile number already associated with the account. This model first gained wide traction in digital content purchases and app stores, where the low amounts made card entry feel disproportionately cumbersome.
The online casino sector was one of the industries that adopted and popularised this approach early. Casino platforms deal in frequent, smaller deposits, the kind of transaction where entering card details every time creates real friction. The pay by phone casino model addressed that directly, letting users deposit by charging their mobile account instead of reaching for a card. There are still plenty of these sites available today, and the format has held its ground because it genuinely makes the process easier.
Digital Wallets and Prepaid Accounts as Transaction Buffers
Digital wallets occupy an interesting position in the payment stack. Services like PayPal, Skrill, and Neteller act as an intermediary layer; users load funds once, then transact repeatedly without re-entering payment details. This buffer model reduces friction at the point of sale while giving users a degree of separation from their main bank account.
Prepaid cards serve a similar function. Loaded with a set amount, they cap spending at the loaded balance and remove the need to share primary account details with every platform a user interacts with. Both formats have grown substantially because they suit the pattern of frequent, small online transactions better than traditional credit or debit cards do in many contexts.
For platforms, accepting wallet payments means integrating with wallet APIs rather than card networks, which often results in faster settlement and fewer chargebacks. The incentive to support these methods goes beyond user preference; it has a measurable effect on payment success rates and operational costs.
Instant Payouts and the Pressure on Settlement Speed
Faster deposits created an expectation for faster withdrawals. Users who can top up an account in seconds are increasingly unwilling to wait two to five business days for a withdrawal to clear. This pressure has pushed infrastructure providers to develop instant or near-instant payout capabilities that work within existing regulatory frameworks.
Visa Direct and Mastercard Send are two examples of push payment rails that move funds to a card in minutes rather than days. Open banking also supports instant outbound transfers in markets where the infrastructure is in place. For platforms that handle high withdrawal volumes, the ability to process payouts quickly is now a competitive factor, not just an operational detail.
The direction is clear: settlement times that were standard five years ago are now considered slow. Infrastructure is being rebuilt around the assumption that both inbound and outbound payments should complete in under a minute.
Payment infrastructure is no longer a back-end concern. It directly shapes what users are willing to do, how often they transact, and which platforms they return to. The systems that handle faster, smaller payments are the ones determining where digital commerce actually happens.